[해외시장조사보고서] “미국 전역서 물재이용 인프라 투자 급증”
블루필드리서치, “미국 지자체 물재이용 관망(Pipeline) 등 인프라 자본지출 2035년까지 평균 471억 달러 전망”
첨단 처리 기술·시설분야 자본지출 42.3%…송수관망 40.4%·엔지니어링 12.4% 차지
물재이용, 공공시설·지자체·산업체 회복탄력성 있는 물공급 계획의 중요한 초석
미국 전역 도시용수 재이용, 핵심 동력으로 빠르게 부상…물문제 해결에 물재이용이 결정적 역할 기대
라우던워터, 32km의 재이용수 전용 송수관망 통해 매년 8억갤런(302만8천329㎥) 이상의 재이용수 공급
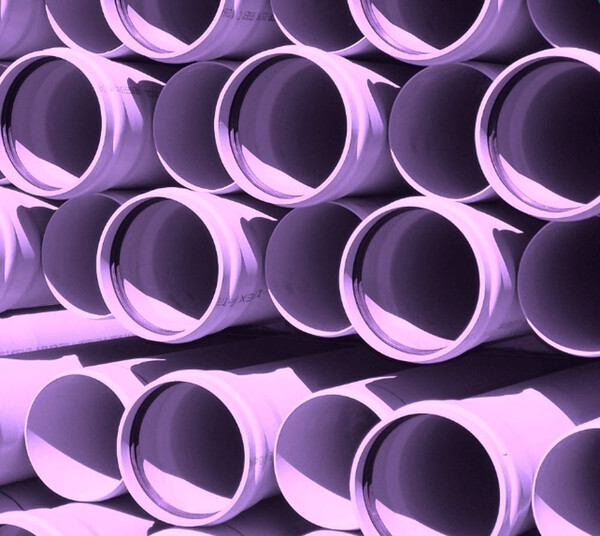
미국 보스턴에 있는 글로벌 시장조사기관인 블루필드 리서치(Bluefield Research)의 새로운 보고서에 따르면, 지자체 물재이용 인프라 및 처리 시스템에 대한 자본지출(CAPEX)은 2025년부터 2035년까지 평균 471억 달러(약 67조3천860억 원)에 이를 것으로 전망된다. 자본지출(CAPEX)의 가장 큰 비중은 10년 전망의 42.3%를 차지하는 첨단 처리 기술 및 시설에 집중될 것으로 예상되며, 재이용수 송수관망(보라색 관)과 엔지니어링 및 설계는 각각 전체 지출의 40.4%와 12.4%를 차지할 것으로 전망된다. [사진출처(Photo Source) = 블루필드 리서치(Bluefield Research)]
처리된 하·폐수를 유익한 용도로 재활용하는 과정인 물재이용은 공공시설, 지자체, 산업체의 회복탄력성 있는 물공급 계획의 중요한 초석이 되며, 미국 전역의 인프라 투자 급증을 촉진시킬 잠재력을 가지고 있다.
세계 물시장 데이터 및 통찰력(Insights)을 제공하는 미국 보스턴에 있는 글로벌 시장조사기관인 블루필드 리서치(Bluefield Research)의 새로운 보고서, ‘미국 지자체 물 재이용 : 시장 동향 및 예측 2025∼2035년(U.S. Municipal Water Reuse : Market Trends and Forecasts 2025∼2035)’에 따르면, 지자체 물재이용 인프라 및 처리 시스템에 대한 자본지출(CAPEX)은 2025년부터 2035년까지 10년간 평균 471억 달러(약 67조3천860억 원)에 이를 것으로 전망된다.
특히, 지출의 가장 큰 비중은 10년 전망의 42.3%를 차지하는 첨단 처리 기술 및 시설에 집중될 것으로 예상되며, 재이용수 송수관망(즉, 보라색관, Purple pipe)과 엔지니어링 및 설계는 각각 전체 지출의 40.4%와 12.4%를 차지할 것으로 전망된다.
이러한 긍정적인 전망의 근간에는 개발 계획 및 실행 단계, 주 정부 정책의 발전, 변화하는 도시, 농업 및 산업용수 수요에 대한 600개 이상의 프로젝트가 있다.
미국 누적 용량 추가 프로젝트 지출(Offtake Application별, 2025∼2035년)
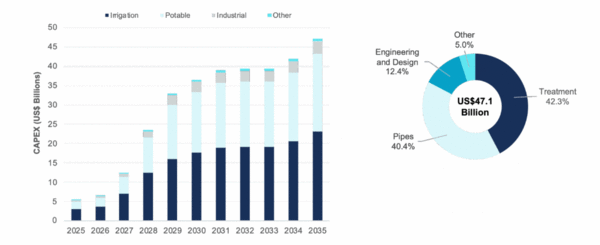
[그림출처(picture source) = 블루필드 리서치(Bluefield Research)]
음용수 재이용이 주류로 향하고 있다
다른 국가에서도 대규모로 시행되고 있지만, 휴대용 음용수 재이용 시스템(Potable Reuse System)의 보급이 점차 확대됨에 따라 미국 시장은 독보적인 위치를 차지하고 있다. 2035년까지 음용수 재이용 프로젝트는 전체 신규 재이용 용량 증가분의 37.0%를 차지할 것으로 예상되며, 이는 일부 지역사회에서 고부가가치 공급 탄력성 애플리케이션으로의 전략적 전환을 시사한다. 관련 자본지출은 199억 달러(약 28조4천709억 원)를 초과할 것으로 예상된다.
이러한 변화의 배경에는 주 정부 정책의 필수적인 변화가 있으며, 이는 물재이용 개발의 주요 원동력이다. 지난 5년 동안 최고 수준의 처리 및 모니터링이 필요한 '직접 음용이 가능한 재이용(DPR)'이 더욱 활성화되었다.
콜로라도, 캘리포니아, 플로리다, 애리조나주는 관련 규정을 제정했으며, 뉴멕시코, 유타, 캔자스, 네바다 등 4개 주는 ‘직접 음용이 가능한 재이용(Direct Potable Reuse, DPR) 시범 프로그램’과 새로운 프로젝트 지침(New Project Guideline)을 적극적으로 검토하고 있다.
농작물 관개, 도시 조경, 도시 녹지공간 조성 등 관개 시설에 대한 재이용 투자는 향후 10년간 자본 지출의 거의 절반(49%)을 차지할 것으로 예상된다.
블루필드 리서치(Bluefield Research)의 메건 본다(Megan Bondar) 분석가는 “관개시설이 물재이용의 기본이 되는 것은 사실이지만, 캘리포니아 오렌지카운티의 ‘지하수 보충 시스템(Groundwater Replenishment System)’이나 버지니아 햄튼 로드 위생 지구(Virginia’s Hampton Roads Sanitation District)의 ‘미래를 위한 지속가능한 물 계획(Sustainable Water Initiative for Tomorrow, SWIFT)’ 프로젝트와 같은 대규모 음용수 재이용 프로젝트는 지방 자치 단체의 정책 결정권자들의 수용성 변화를 보여주고 있다”라고 말했다.
물재이용의 지형이 변화하고 있다
2012년부터 2017년까지 이어진 가뭄과 의무적인 물 사용량 감축을 계기로 캘리포니아주의 ‘프로젝트 파이프라인(Project Pipeline)’이 확장되었다. 캘리포니아주는 향후 10년간 재이용 용량 증설에서 플로리다주를 앞지를 것으로 예상되며, 신규 재사용 용량 증가분의 41%를 차지할 것으로 예상된다.
콜로라도, 텍사스, 플로리다주 또한 상당한 성장세를 보일 것으로 예상되는데, 인구 증가와 대수층 과다 사용으로 인해 예상 신규 용량의 45%를 차지할 것으로 예상된다.
앞으로 미국 서부지역은 도시의 물재이용 용량 증설의 중심지로, 약 390개의 프로젝트가 다양한 계획 단계에 있다. 그러나 남동부 지역은 이미 약 3분의 1의 프로젝트가 건설 중이며 입지를 굳건히 하고 있다.
메건 본다(Megan Bondar) 분석가는 “현재 버지니아, 뉴욕, 뉴저지 등 미국 중서부와 동부 해안지역 여러 주에서 동쪽으로의 추진력이 두드러지고 있다”라면서 “미국 서부 지역의 프로젝트들이 주로 가뭄 회복력 강화에 중점을 두는 것과 달리, 이러한 이니셔티브들은 수질 개선과 주요 대수층으로의 염수 침투 속도 감소에 더 중점을 두는 경향이 있다”고 강조했다.
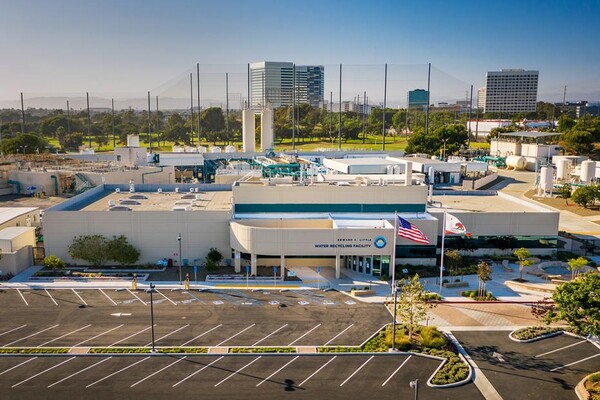
캘리포니아주는 향후 10년간 재이용 용량 증설에서 플로리다주를 앞지를 것으로 예상되며, 신규 재사용 용량 증가분의 41%를 차지할 것으로 예상된다. 사진은 웨스트베이슨이 운영하는 에드워드 C. 리틀 물재이용 시설(Edward C. Little Water Recycling Facility). [사진출처(Photo Source) = 웨스트베이슨 수도국(West Basin Municipal Water District)]
산업계 파트너십, 물재이용 경제성 점진적 재정의
산업 수요는 도시용수 재이용의 핵심 동력으로 빠르게 부상하고 있다. 특히 9개 산업 부문에서 경제적 물부족 현상이 가장 높은 뉴멕시코주, 애리조나주, 네바다주 서부지역을 중심으로 물부족 현상이 심화됨에 따라, 공공 서비스 업체와 민간 시설 운영업체들은 공급 확보 및 성장 지속을 위해 파트너십을 구축하고 있다.
데이터센터 개발업체들은 이러한 변화의 선두에 서 있다. 특히 주요 운영업체가 사용하는 물의 97%가 도시용수 업체에서 공급 및 처리되기 때문이다. 세계에서 가장 집중된 데이터센터 시장 중 하나인 버지니아주에 서비스를 제공하는 라우던 워터(Loudoun Water)는 전용 20마일(약 32km) 길이의 재이용수 송수관망(Purple Pipe Network)을 통해 매년 8억 갤런(약 302만8천329㎥) 이상의 재이용수를 공급하고 있다.
메건 본다(Megan Bondar) 분석가는 “이론적으로 볼 때, 산업 시설이 하수공공기업의 하수처리수를 직접 공급하는 것이 전략적으로 타당하고, 처리수는 그렇지 않으면 강이나 다른 지표수로 방류될 것”이라면서 “하지만, 실행은 복잡한 경우가 많으며, 여러 이해관계자 간의 협력으로 인해 프로젝트 완료에 장애가 발생할 수 있다”고 강조했다.
앞으로 물재이용은 미국이 점차 심화되는 물문제 해결에 결정적인 역할을 할 것으로 예상된다. 이러한 변화에는 정책 추진력, 기술 혁신, 그리고 산업 수요의 조화가 매우 중요하다. 공공 서비스 제공업체, 지역사회, 그리고 민간 파트너들이 물의 공급, 관리 및 가치 평가 방식을 재고함에 따라, 물재이용은 주변부에서 주류로 더욱 확대될 것으로 예상된다.
미국 보스턴에 있는 글로벌 시장조사기관인 블루필드 리서치(Bluefield Research)는 전 세계 산업 및 지자체 부문의 전략적 의사 결정권자들에게 실행 가능한 물시장 정보와 데이터를 제공하고 있으며 인프라, 정책, 기술 전반에 걸친 전문지식을 바탕으로 블루필드 리서치는 기업들이 시장의 미래와 그 이유를 이해할 수 있도록 지원하고 있다.
‘미국 지자체 물 재이용 : 시장 동향 및 예측, 2025∼2035년(U.S. Municipal Water Reuse: Market Trends and Forecasts 2025∼2035)’ 보고서는 시장 동향, 정책 개발, 그리고 전략적 전환이 도시 물재이용 인프라에 대한 투자 환경을 어떻게 변화시키고 있는지에 대한 데이터 기반 관점을 제시하며, 미국 22개 주에 걸쳐 추적된 1천 개 이상의 재사용 프로젝트 데이터 세트를 활용했다.
[원문보기]
U.S. Water Reuse Pipeline to Drive US$47.1 Billion in Infrastructure Spending Through 2035
23 October 2025, Boston, Massachusetts - Water reuse?the process of recycling treated wastewater for beneficial uses-represents a viable cornerstone of resilient water supply planning for utilities, municipalities, and industries, unlocking a potential surge in infrastructure investment across the U.S.
According to a new Insight Report, U.S. Municipal Water Reuse: Market Trends and Forecasts, 2025?2035, from Bluefield Research, a leading provider of global water market data and insights, capital expenditure (CAPEX) for municipal reuse infrastructure and treatment systems are forecasted to average US$47.1 billion from 2025 through 2035.
The largest share of spending will be directed toward advanced treatment technology and facilities, which account for 42.3% of the ten-year outlook. Conveyance pipe networks (i.e., purple pipes) and engineering and design account for 40.4% and 12.4% of spending, respectively.
Underlying this positive outlook are more than 600 projects in the planning and execution phases of development, advancements in state-level policies, and changing urban, agricultural, and industrial water needs.
Potable Reuse Moves Toward Mainstream
While demonstrated at scale in other countries, the increasingly widespread deployment of potable reuse systems makes the U.S. market unique. By 2035, potable reuse projects are expected to account for 37.0% of all new reuse capacity additions, signaling a strategic shift toward higher-value, supply-resilient applications for some communities. Associated capital expenditures are forecasted to surpass US$19.9 billion.
Behind this shift are necessary changes in state-level policies, which are the primary enablers of reuse development. Over the past five years, direct potable reuse (DPR), which requires the highest levels of treatment and monitoring, has gained added momentum. Colorado, California, Florida, and Arizona have established regulations, and four additional states-New Mexico, Utah, Kansas, and Nevada-are actively exploring DPR pilot programs and new project guidelines.
Reuse investment for irrigation applications - ranging from crop watering and urban landscaping to municipal green spaces-is still projected to account for nearly half (49%) of capital expenditure over the next decade.
“While irrigation applications make up the foundational application for water reuse, large potable reuse projects such as the Groundwater Replenishment System in Orange County, California, and the [Sustainable Water Initiative for Tomorrow] SWIFT project in Virginia’s Hampton Roads Sanitation District are showcasing a change in receptiveness among municipal decision makers,” says Megan Bondar, an analyst at Bluefield Research.
The Geography of Reuse Is Changing
Catalyzed by the 2012-2017 drought, including mandated water usage cuts, California’s project pipeline has expanded. The state is projected to surpass Florida in terms of reuse capacity buildout over the next 10 years, accounting for 41% of new reuse capacity additions.
Colorado, Texas, and Florida are also poised for significant growth, collectively accounting for 45% of projected new capacity?linked to rising populations and overdrawing from aquifers.
Looking forward, Western U.S. states remain at the epicenter of municipal reuse buildout, with nearly 390 announced projects in various stages of planning. However, the Southeast is gaining ground, with almost one-third of projects already under construction.
“We’re now seeing a pronounced eastward momentum within the Midwest and several East Coast states-including Virginia, New York, and New Jersey,” explains Bondar.
“Unlike projects in the Western U.S., which are primarily driven by drought resilience, these initiatives tend to focus more on improving water quality and slowing the advance of saltwater intrusion into critical aquifers.”
Industry Partnerships Incrementally Redefine Reuse Economics
Industrial demand is rapidly emerging as a key driver of municipal water reuse. As water stress intensifies - particularly in the Western states of New Mexico, Arizona, and Nevada, which rank highest for economic water stress across nine industrial sectors-utilities and private facility operators are forming partnerships to secure supply and sustain growth.
Data center developers have moved to the forefront of this shift, particularly since 97% of water used by major operators is sourced and treated by municipal utilities. In Virginia, Loudoun Water-serving one of the world’s most concentrated data center markets-delivers more than 800 million gallons of reclaimed water annually through a dedicated 20-mile purple pipe network.
“On paper, it makes strategic sense for industrial facilities to source treated water directly from wastewater utilities-treated water that would otherwise be discharged into rivers or other surface waters,” states Bondar. “That said, execution is often complex, with multi-stakeholder coordination creating hurdles to project completion.”
Looking ahead, water reuse is set to play a defining role in how the U.S. addresses its growing water challenges. The alignment of policy momentum, technological innovation, and industrial demand will be critical to this transformation. As utilities, communities, and private partners rethink how water is sourced, managed, and valued, reuse will move further from the margins to the mainstream.
About Bluefield Research
Bluefield Research supports strategic decision makers with actionable water market intelligence and data in the global industrial and municipal sectors. With expertise spanning infrastructure, policy, and technology, Bluefield helps companies understand where the market is going-and why.
This Insight Report, U.S. Municipal Water Reuse: Market Trends and Forecasts, 2025-2035, presents a data-driven perspective on how market trends, policy developments, and strategic pivots are reshaping the investment landscape for municipal reuse infrastructure, leveraging a dataset of more than 1,000 tracked reuse projects across 22 U.S. states. The full report is available for purchase and immediate download from Bluefield’s website.
[출처= 블루필드 리서치(Bluefield Research)(https://www.bluefieldresearch.com/ns/u-s-water-reuse-pipeline-to-drive-us47-1-billion-in-infrastructure-spending-through-2035/) / 2025년 10월 23일]
 즐겨찾기 추가
 시작페이지로 설정